VA Loan Home Buyers in Wake County, NC: How to Write an Offer Sellers Accept in 2026
Real Estate
Real Estate
A VA offer wins in Wake County in 2026 when it is priced to current comps, backed by a fully underwritten preapproval, and presented by an agent who frames zero-down financing as a strength, not a risk.
VA rates ran roughly 6.25% to 6.59% in mid-September 2026, below the 6.76% conventional average, with zero down payment and no monthly mortgage insurance.
The first-use VA funding fee is 2.15% of the loan (financed, not paid at the table) and is waived entirely for veterans with a service-connected disability rating.
Wake County's August 2026 median sale price was $440,000, inventory sits near a balanced five-plus months, and homes are taking roughly 45 to 50 days to sell, which hands buyers real negotiating leverage.
VA-friendly Wake County areas near Research Triangle Park and RDU include Cary, Apex, Morrisville, Holly Springs, Wake Forest, Garner, and Wendell.
North Carolina adds real value: 100% service-connected disabled veterans can exclude $61,000 of home value from property tax (raised July 1, 2026), and military retirement pay is state-tax-free.
More Wake County buyer resources are at lisaquin.com.
Opening
A VA loan offer wins in Wake County in 2026 when it is priced to current comps, backed by a fully underwritten preapproval, and presented by an agent who frames zero-down financing as the strength it actually is. Lisa Quin, founder of Quin Realty Group at Compass, has spent more than 20 years guiding buyers and sellers across Wake County, from Cary and Apex to Holly Springs and Wake Forest. Many of the veterans and military families Lisa works with arrive with the same quiet worry. They assume a VA offer looks weaker than cash or conventional, so a seller will pass them over. In today's balanced Wake County market, that fear is mostly outdated. This guide covers how a VA buyer writes an offer sellers accept, what those sellers are really weighing, and how to use current local leverage. For more Wake County buyer guides, start at lisaquin.com.
The problem is rarely the VA loan itself. It is the story that has followed VA financing around for years. Somewhere along the way, VA offers picked up a reputation for slow closings, tough appraisals, and long repair lists. A generation of listing agents learned to steer sellers toward conventional or cash. That reputation has not kept up with reality, and it costs veterans homes they could have won.
Here is what a Wake County veteran is actually up against. It is not that sellers hate VA loans. It is that a nervous seller, or an under-informed listing agent, hears "VA" and imagines friction. When two offers land at similar prices, that imagined friction can tip the scale. So the real problem is perception, and perception is something a skilled agent can manage.
The good news is that the 2026 market works in a veteran's favor. Inventory across Wake County is the highest it has been in years, homes are sitting longer, and sellers are more open to a well-qualified, motivated buyer than they were in the frantic years. A VA buyer who shows up prepared, priced right, and clearly represented is not the risky offer in the pile. Lisa has watched that shift happen deal by deal, and it changes how a veteran should approach the whole process.
A winning VA offer in Wake County is built, not hoped for. Lisa Quin walks veteran buyers through a clear sequence so the offer lands as the strong, safe choice on the table:
Get a fully underwritten preapproval, not a quick prequalification. A prequalification is a guess. A fully underwritten preapproval, where a VA-experienced lender has already reviewed income, credit, and entitlement, tells a seller this buyer will close. That single document neutralizes most VA hesitation before it starts.
Price the offer to real, current comps. In a balanced market, a clean offer at the right number beats a stretched offer with strings. Lisa pulls recent sales in the exact neighborhood and price band so the number holds up at appraisal.
Ask for seller-paid closing costs instead of overpaying. VA buyers can have sellers cover closing costs and certain fees. Structuring a fair price with a seller credit often nets the veteran more than piling extra dollars onto the sale price.
Keep due diligence and earnest money credible. North Carolina uses a due diligence fee and an earnest money deposit rather than traditional contingencies. A reasonable, well-placed due diligence fee signals a serious buyer without requiring cash the veteran does not need to spend.
Use the VA appraisal and inspection as tools, not obstacles. The VA appraisal protects the buyer with Minimum Property Requirements. A prepared agent flags likely repair items early and knows how to handle a low appraisal or a Tidewater notice so the deal keeps moving.
Let the agent educate the listing agent. Half the battle is a quick, confident conversation that answers a listing agent's VA questions before they harden into a reason to say no. That is representation doing its job.
The through-line is preparation. Every step above exists to replace a seller's worry with evidence.
Wake County in the second half of 2026 is a genuinely different market than the one veterans may remember hearing about. The county's median sale price was $440,000 in August 2026, down from $458,500 in July, and inventory has climbed into balanced territory near five months of supply or more. Homes are taking roughly 45 to 50 days to sell rather than flying off the market in a weekend. For a VA buyer, that combination means time to tour, room to negotiate, and far less pressure to waive protections just to compete.
Rates help too. In mid-September 2026, VA purchase rates ran around 6.25% to 6.59% depending on the lender and the day, sitting below the 6.76% average for a conventional 30-year loan. Pair that lower rate with zero down and no monthly mortgage insurance, and a veteran's monthly payment can undercut a conventional buyer at the same price.
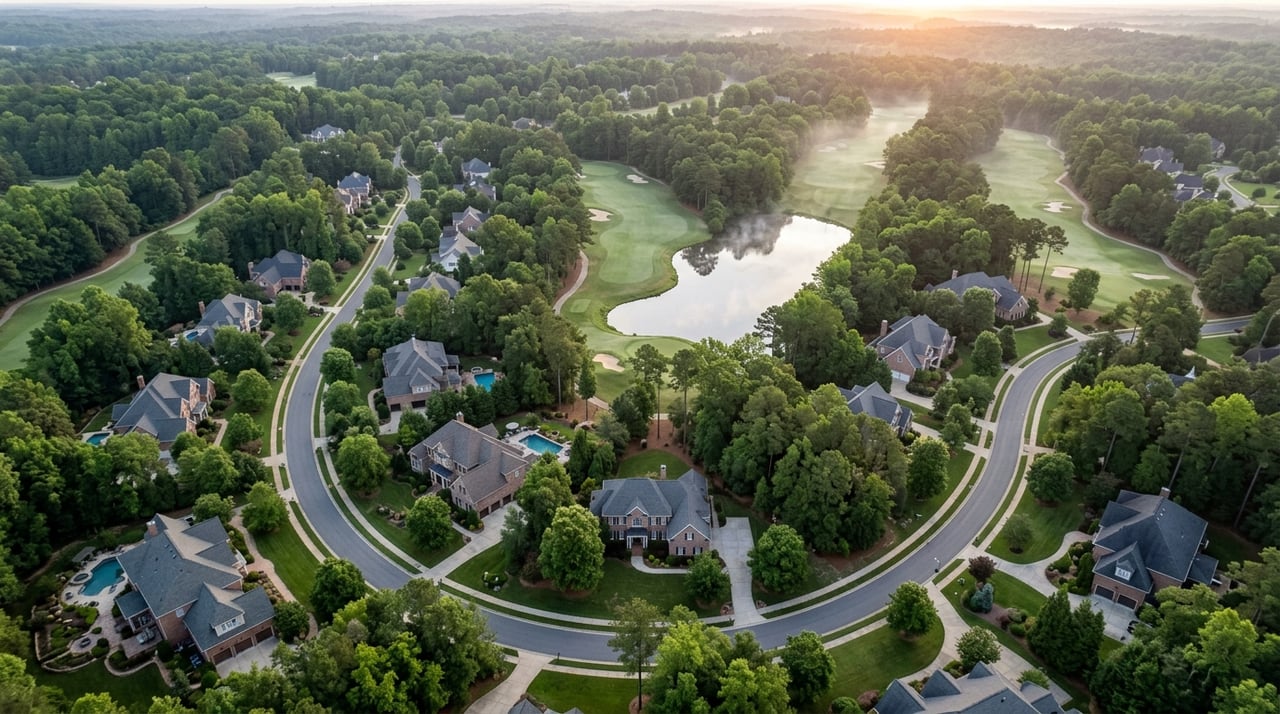
Where a veteran looks depends on the job and the commute. For families relocating to Research Triangle Park or working near RDU, Cary, Morrisville, and Apex offer short drives and strong schools. Holly Springs blends golf communities like 12 Oaks with newer, value-friendly neighborhoods. To the north, Wake Forest carries small-town charm 20 minutes from Raleigh. For lower entry prices and zero-down-friendly budgets, Garner, Wendell, and the fast-growing Wendell Falls community stretch a VA buyer's dollar further east and south. North Carolina also stacks real benefits on top of the loan, from tax-free military retirement pay to property tax relief for disabled veterans, and Lisa walks through several of them in her video on top veteran benefits in North Carolina. To see current listings across these towns, browse lisaquin.com/properties.
Even strong VA buyers lose homes to avoidable errors. These are the ones Lisa sees most often in Wake County:
Treating a prequalification as a preapproval. A prequalification carries almost no weight with a seller. Walking in with a fully underwritten VA preapproval is the single biggest edge a veteran can hold, and skipping it hands the advantage to the next buyer.
Overpaying to look strong. In a balanced market, stretching the price to seem aggressive backfires when the VA appraisal comes in lower. A right-priced offer with a seller credit is usually the smarter, stronger play.
Waiving inspections to compete. VA buyers have real protections through the appraisal and Minimum Property Requirements. Gutting inspection rights to mimic a cash offer trades away the very safeguards that make VA financing safe.
Ignoring the funding fee math. The first-use funding fee is 2.15% and is financed into the loan, but veterans with a service-connected disability rating are exempt entirely. Not knowing which category applies can throw off the whole budget.
Hiring an agent who has never closed a VA deal. VA financing has its own rhythm, from Tidewater appraisal notices to allowable fees. An agent who has not lived through it cannot reassure a nervous listing agent, and that silence can cost the house.
Winning with a VA loan is less about luck and more about representation, and that is exactly where Lisa Quin's experience earns its keep. A Louisiana native who has called the Triangle home since the late 1980s and raised her family in Cary, Lisa has spent more than 20 years learning how Wake County sellers think and how to position a buyer as the safe, serious choice. She is a member of the Raleigh Association of REALTORS Top Producers Council and the Women's Council of REALTORS, and she treats every purchase as a relationship rather than a transaction. As Lisa puts it, "Real estate often is about guiding people through complex situations."
That guiding instinct matters most in the quiet moments a veteran never sees, like the phone call where Lisa answers a listing agent's VA questions before they become a reason to reject an offer. One of Lisa's VA clients felt that difference firsthand. Jennifer C., a first-time buyer who used a VA loan to move to the Triangle from out of state, wrote that Lisa "broke down the triangle into manageable parts" and helped them get an accepted offer under asking. When a difficult VA appraisal required installing 150 linear feet of railing on a retaining wall and passing inspection in under three weeks to close, Lisa found a contractor when no one else would call back. As Jennifer wrote, "Without her, there's no way we would have made our closing date." That is the whole job in a veteran's case, taking a loan product some sellers still misunderstand and presenting it as the strength it is. You can read more client stories at lisaquin.com/testimonials.
Do Wake County sellers still reject VA offers in 2026? Some hesitate, but far fewer than the old reputation suggests. VA buyers are among the most likely to reach closing, and in a balanced market with more inventory, sellers value a well-qualified, motivated buyer. Lisa's job is to remove the doubt before it costs the veteran the home.
How much cash does a VA buyer need up front in Wake County? Often much less than buyers expect. VA loans require zero down payment and no monthly mortgage insurance, so the main out-of-pocket costs are the North Carolina due diligence fee, earnest money, and any closing costs not covered by a seller credit. Lisa helps structure the offer so those numbers stay manageable.
Are VA loans slower to close? Not meaningfully anymore. With a VA-experienced lender, VA loans commonly close in the same 30 to 45 day window as conventional loans. The key is choosing a lender who closes VA deals regularly, which Lisa can help arrange.
What is the VA funding fee and can it be avoided? The funding fee is a one-time cost, 2.15% of the loan for first-use buyers with no down payment, and it is financed into the loan rather than paid at closing. Veterans receiving compensation for a service-connected disability are exempt from it entirely.
Is there a VA loan limit in Wake County? For veterans with full entitlement, there is no VA loan limit. That means a qualified veteran can buy across most of Wake County's price range with zero down, subject to the lender's approval of income and credit.
Can I use a VA loan on new construction in Wake County? Yes, and eastern and southern Wake County towns like Wendell, Garner, and Fuquay-Varina have active new-construction communities. The home and builder must meet VA requirements, so working with an agent who knows which builders and lenders are VA-ready saves time.
What North Carolina benefits do veterans get beyond the loan? Military retirement pay is exempt from North Carolina state income tax, and 100% service-connected disabled veterans can exclude $61,000 of their home's value from property taxes, a figure raised effective July 1, 2026. The Durham VA Health Care System and a Raleigh VA clinic also put care close to home.
Buying a home with a VA loan in Wake County should feel like the benefit it was meant to be, not a source of worry. The 2026 market gives veterans more choice, more time, and more leverage than they have had in years, and the right offer strategy turns that leverage into keys in hand. If a move to the Triangle is on the horizon, whether that is in the next few weeks or sometime next year, a short conversation now can save real money and stress later. Lisa Quin is glad to walk through your entitlement, your budget, and the neighborhoods that fit your commute, with no pressure and no obligation. Reach out through lisaquin.com/team to start the conversation.
Real Estate

Real Estate
Real Estate
Real Estate
With over 20 years of real estate experience in the Triangle area of NC, Quin Realty Group will give you a full-service experience in purchasing or selling your home! Consider us your personal home concierge!
201 FENTON GATEWAY DR CARY NC 27511